Insights · 2026-09-09
Lessons Learned from the Wesley Trust Case and the Interpretation of the New Domestic Circular No. 21
◆ 01|Case Background: Not a 1990 Judgment ◆
Wesley and Mackay v HMRC (Ellen Morris 1990 Settlement Trust)
The trust instrument is named Ellen Morris 1990 Settlement, hence widely known as the “1990 Wesley Case”. The First-tier Tribunal (FTT) tax hearing was held in 2014, and judgments were handed down by the Chancery Division in Mackay v Wesley [2020] EWHC 1215 / EWHC 3400. The ruling was not made in 1990; the trust deed was executed in 1990.
◆ 02|Full Facts of the Case ◆
1 Trust Vehicle: The Ellen Morris 1990 Settlement was established in the Isle of Man in 1990. David Wesley was the principal beneficiary, and the trust carried substantial unrealised capital gains on its books.
2 Round-the-World Tax Avoidance Scheme: Implemented in the 2002–03 tax year. The Isle of Man trustee retired and was replaced by a Mauritian trustee. Assets were disposed of in Mauritius to realise capital gains, taking advantage of Mauritius’ no-tax regime. Within the same tax year, the trustee was switched back to a UK-resident trustee, seeking to circumvent the anti-avoidance provision under Section 86 of the Taxation of Chargeable Gains Act 1992 (TCGA 1992).
3 Daughter Appointed Under Crisis: The original plan was for Mr. and Mrs. Wesley to serve as UK trustees. Since Mrs. Wesley was diagnosed with terminal cancer, their daughter Nicola Mackay was arranged to take over as the UK trustee. Nicola was emotionally vulnerable after losing her child, obtained no independent legal advice, and signed the acceptance of appointment under her father’s influence. At the time of her appointment, only £61,000 of trust assets remained, yet she inherited tax liabilities arising from the entire suite of prior transactions.
4 HMRC Recovery: Citing the Smallwood precedent, HMRC held that the entire round-the-world tax avoidance scheme was invalid. The trustees bore joint and several liability for £1.6 million in Capital Gains Tax (CGT), and HMRC pursued recovery against David Wesley and Nicola Mackay.
◆ 03|Two Parallel Proceedings ◆
First-tier Tribunal (FTT): Wesley & Mackay v HMRC This proceeding examined the validity of the cross-border tax avoidance scheme. The tribunal ultimately ruled the tax arrangement ineffective and the tax payable.
Chancery Division: Mackay v Wesley
The daughter filed a claim to rescind her acceptance of trusteeship. The claim was dismissed at first instance, but the appeal succeeded: the father was found to have exercised presumed undue influence. Nicola’s acceptance of appointment as trustee was rescinded, releasing her from the £1.6 million joint and several tax liability. The validity of the trust itself and of the other trustees remained unaffected.
Core lesson: Never sign documents to act as trustee of a family trust without first consulting independent legal counsel.
◆ 04|Comparison with Announcement No.21 (2026) issued by the Ministry of Finance and State Taxation Administration ◆
Commonalities
1. Trust relocation or trustee replacement cannot wipe out historical tax liabilities
Wesley Case: The trust moved from the Isle of Man to Mauritius and then to the UK with multiple trustee replacements. Historical capital gains tax obligations attach to the trust and do not disappear merely because trustees resign or asset values shrink.
Announcement No.21: Relocation of offshore trusts or replacement of offshore trustees does not eliminate tax liabilities of Chinese tax-resident settlors. Historical gains must be declared, and structural changes do not exempt prior tax obligations.
2. Pierce the legal form to examine substantive control and disregard artificial tax avoidance structures
Wesley Case: Although capital gains were formally realised by the Mauritian trustee, UK HMRC pierced the structure and ruled that UK trustees were liable for CGT.
Announcement No.21: Chinese tax authorities look past the formal legal ownership of trust assets held by offshore trustees and look through to the Chinese resident settlor. Tax applies to trust funding, ongoing income, distribution and liquidation stages; tax avoidance arrangements will not be recognised.
3. High risks for family members acting as nominee trustees
Wesley Case: The asset-poor daughter was appointed trustee to facilitate the scheme and became subject to joint liability for over one million pounds. Mere ignorance of legal consequences did not constitute a defence; relief was granted only upon proof of undue influence.
Announcement No.21: Identity information will be exchanged under CRS where relatives act as trustees or protectors. Nominee status does not remove the Chinese settlor’s tax obligations. Nominee trustees may be drawn into tax investigations and bear duties to submit information and assist with tax collection.
4. Signed documents carry significant legal consequences; prior independent professional advice is critical
Wesley Case: Signing to accept trusteeship triggers liability. Without independent legal advice, the signatory faces substantial risks.
Announcement No.21: All signed documents for trust establishment, amendment, relocation and distribution serve as the basis for tax determination. Chinese residents setting up offshore trusts must obtain both domestic tax advice and overseas legal opinions.
Key Differences
1. Different statutory taxpayers Wesley Case (UK): Trustees are statutory taxpayers with joint and several liability for capital gains tax. The tax authority directly collects tax from trustees, who may then seek indemnity from beneficial beneficiaries.
Announcement No.21 (China): Chinese resident settlors are statutory individual income taxpayers. Offshore trustees mainly undertake information reporting and assistance obligations and are not primary taxpayers.
2. Different remedy avenues Wesley Case: Under UK equity law, where the elements of undue influence are satisfied, acceptance of trusteeship may be rescinded, retroactively releasing that trustee from tax debt. This does not eliminate the underlying tax liability of the trust.
Announcement No.21: Rescission of a trustee’s status by a foreign court does not release the Chinese resident settlor from tax obligations. It may only relieve the nominee trustee of assistance duties. The settlor’s tax liability remains unaffected by foreign court judgments.
◆ 05|Practical Takeaways & Warnings ◆
1 Do not appoint asset-poor family members as trustees of offshore trusts. Even under offshore structures, incoming trustees assume risks for all historical tax liabilities of the trust.
2 Trust relocation or trustee replacement cannot be used to evade filing obligations under China’s Announcement No.21. Historical income must still be declared.
3 Before family members sign trust-related documents, independent tax and legal advice must be obtained. Verbal assurances of “no risk” cannot be used as a defence.
4 For existing legacy offshore trusts, review records of trust relocation and trustee changes to identify structures similar to the “round-the-world tax avoidance scheme”. Consult qualified tax professionals to complete declarations within the compliance window and mitigate late surcharges and penalties.
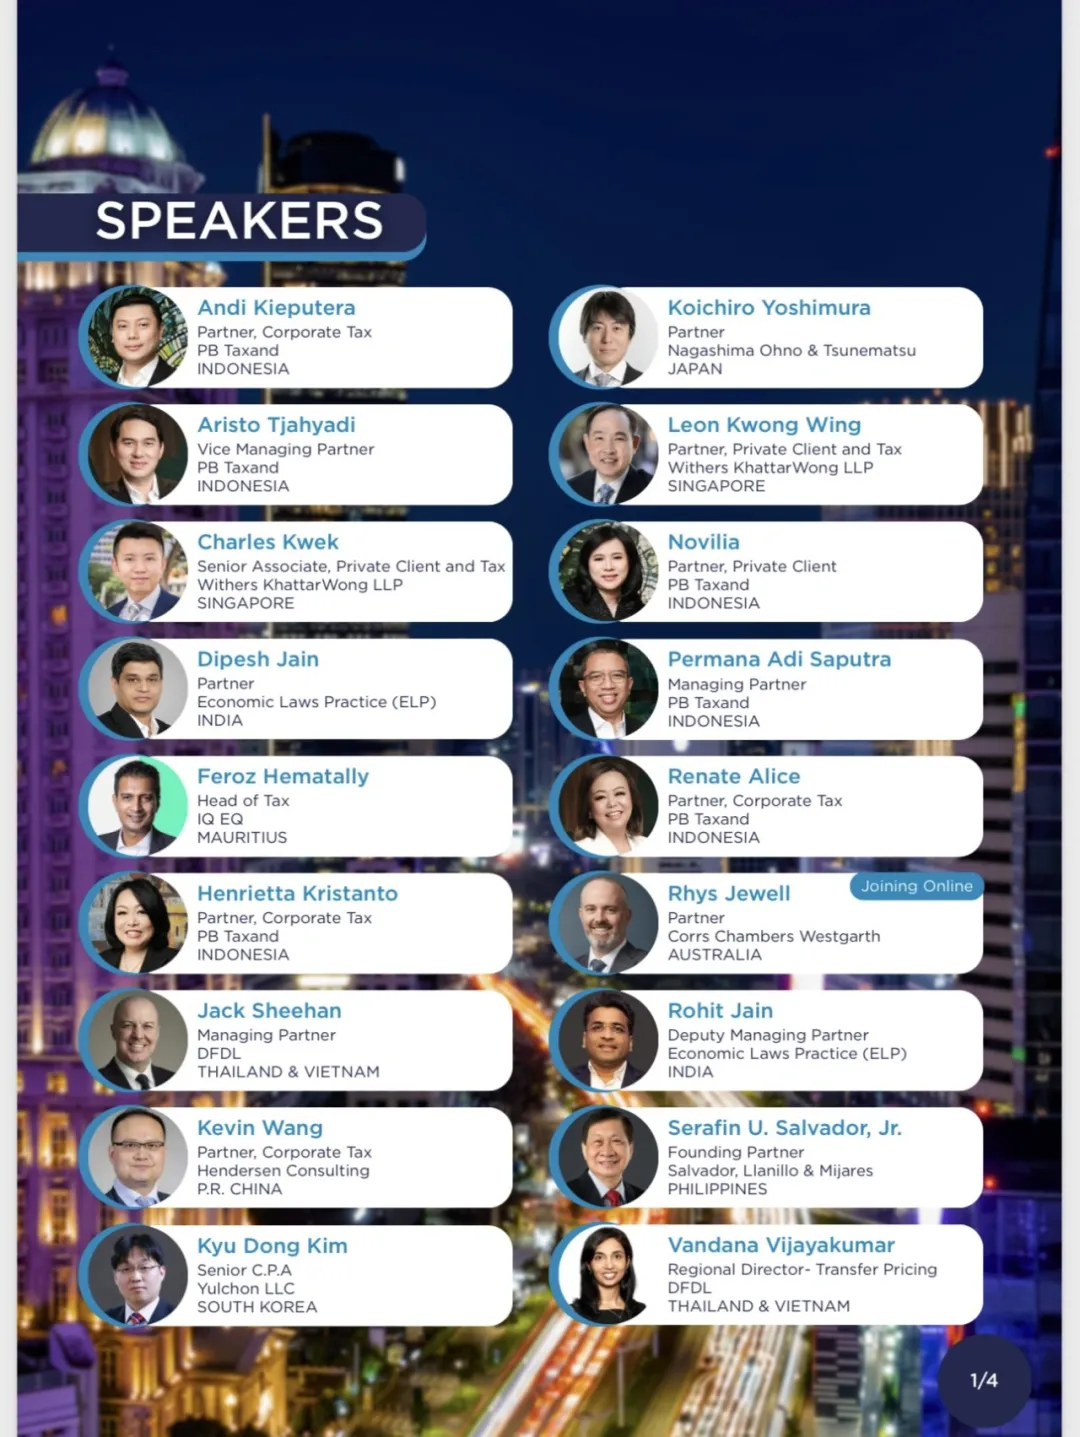
◆ 06|Speaker Partner ◆
Related insights
- 2026-08-27State Taxation Administration Issues Document Clarifying Collection and Administration Issues Concerning Income Tax Treatment of Enterprise Reorganization
- 2026-07-27【BREAKING】New Offshore Trust Rules
- 2026-07-23When "State Ownership" Is Deemed "Related-Party" Status — A Full Review of MMG's Thin Capitalization Litigation Case in Peru