Taxand Global Alliance · China Member Firm
Your cross-border tax partner in China.
Independent advice on China tax, M&A, transfer pricing and outbound structuring — from a senior team that has done it for 20 years.
Global network
One Chinese partner firm in the world's largest independent tax alliance.
Hendersen is the sole China member of Taxand — 700+ partners, 2,000+ advisers, 54+ countries. Cross-border engagements are coordinated directly with the relevant Taxand firm, with no intermediaries.
Learn about Taxand
What we do
Services
Corporate Tax
China tax compliance and advisory for inbound and outbound structures.
Learn more →Merger & Acquisition
Tax due diligence, deal structuring, valuation support and post-merger integration.
Learn more →Investment Advisory
Cross-border investment planning and tax-efficient holding structures.
Learn more →Outsourcing
Accounting, payroll and tax filings managed end-to-end.
Learn more →Human Capital
Individual income tax, equity incentives, and expatriate tax planning.
Learn more →Customs & Trade
Tariff classification, transfer pricing documentation, customs valuation.
Learn more →Transfer Pricing
TP documentation, benchmarking studies and risk reviews.
Learn more →High Net Worth
Cross-border wealth structuring, estate and succession planning.
Learn more →AI Integration
Embedding AI agents into in-house tax workflows.
Learn more →Insights
Latest from Hendersen
2026-10-18 · Featured
Restructuring of Mixed Sales Rules | VAT Tax Pitfalls for Elevator Enterprises
Effective 1 January 2026, the "Value-Added Tax Law of the People’s Republic of China" shall come into force. Supporting documents including the "Regulations for the Implementation of the Value-Added Tax Law" (State Council Decree No. 826), Announcement No. 13 of 2026 and Announcement No. 9 of 2026 issued by the Ministry of Finance and the State Taxation Administration have been promulgated in quick succession. The elevator industry is subject to VAT rates across three brackets: 13%, 9% and 6%. Misclassification may easily trigger tax risks.
Read full analysis →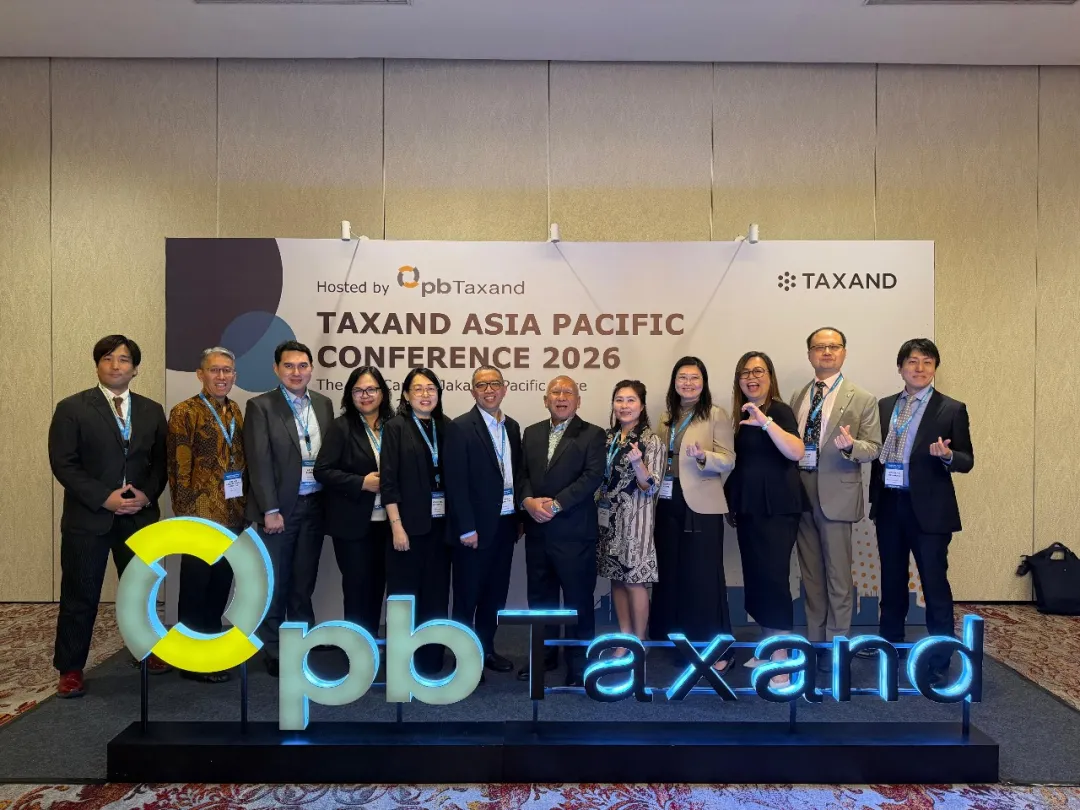
2026-09-09
Lessons Learned from the Wesley Trust Case and the Interpretation of the New Domestic Circular No. 21
PB Taxand (Indonesia Member Firm) successfully hosted the Taxand Asia Pacific Conference 2026 on 31 August 2026 at The Ritz-Carlton, Jakarta, Indonesia. At the conference, Leon Kwong Wing, Partner of Taxand Singapore, and Kevin Wang, Partner of Taxand China, delivered a keynote presentation on the Wesley Trust Case and its tax implications for China.
2026-08-27
State Taxation Administration Issues Document Clarifying Collection and Administration Issues Concerning Income Tax Treatment of Enterprise Reorganization
Recently, the State Taxation Administration issued the “Announcement on Certain Collection and Administration Issues Concerning Income Tax Treatment of Enterprise Reorganization” (2026 No. 13, hereinafter referred to as the “Announcement”). This policy is primarily applicable to enterprises with relatively dispersed equity structures and complex shareholder compositions (including corporate shareholders, individual shareholders, partnerships, etc.), and is also specifically formulated for merger and division transactions of listed companies.
2026-07-27
【BREAKING】New Offshore Trust Rules
On July 24, the Ministry of Finance and the State Taxation Administration jointly issued Announcement No. 21 of 2026, signaling that the individual income tax loophole for offshore trusts has been formally closed. The most critical signal is this: obtaining a foreign identity no longer equates to severing one's Chinese tax obligations. No matter how many layers of “shell” structures are in place, as long as the economic substance ultimately rests with a Chinese individual, the tax treatment must follow China's tax laws to completion.
2026-07-23
When "State Ownership" Is Deemed "Related-Party" Status — A Full Review of MMG's Thin Capitalization Litigation Case in Peru
The Peruvian tax authority advanced an unprecedented legal logic: because MLB's ultimate controlling shareholder, China Minmetals Corporation, is a central state-owned enterprise, and the lending institutions — China Development Bank and The Export-Import Bank of China — are also central state-owned enterprises, both parties are “under the control of the Chinese government,” and therefore they constitute a related-party relationship. If this logic were to prevail, all cross-border transactions among Chinese state-owned enterprises would be redefined.
2026-07-02
Lessons from Jushi Group's Egypt share-transfer case for resolving international tax disputes
When a Chinese listed company transfers the shares of an overseas subsidiary, where should tax be paid — China or the host state? A seemingly simple question once put global fibreglass leader Jushi Group within reach of RMB 140 million in irrecoverable tax. This cross-continental dispute between Asia and Africa ultimately ended with the Chinese position fully accepted by the Egyptian tax authorities. The case offers a textbook example of (i) the priority of bilateral tax treaties over domestic tax law, (ii) the limits of cross-treaty analogy, and (iii) a clean three-step framework for analysing share-transfer taxing rights under the China–Egypt treaty — with the Chinese tax authorities, through provincial and central tax bureaus, securing the favourable outcome.
2026-06-23
Hong Kong's tax transparency moves into criminal enforcement: the first CRS conviction
In March 2026, a Hong Kong court handed down the jurisdiction's first criminal CRS conviction: a private-banking client who made a false statement about the beneficial owner of a Seychelles-incorporated offshore company was sentenced to 6 months' immediate imprisonment and a HKD 500,000 fine. The case marks the moment Hong Kong's CRS supervision moved from administrative enforcement to criminal prosecution. Hong Kong is also accelerating domestic legislation for CRS 2.0 and the Crypto-Asset Reporting Framework (CARF), with administrative-framework amendments expected to take effect on 1 January 2027 and CRS 2.0 full exchange by 2029.